Financial advisor for engineers
Financial planning for engineers in Calgary and across Canada. Kaetyn St. Hilaire, CFA, works through the decisions an engineering career brings: pension elections, commuted values when you change employers, consulting through a corporation and a retirement date you choose.
Engineer pensions: defined benefit, defined contribution and group RRSPs
An employer plan is often the largest asset an engineer owns and the one they read least. The type of plan decides how much RRSP room you have left and what happens when you move.
Defined benefit pensions
A defined benefit plan promises an income based on your salary and years of service. It also creates a pension adjustment each year that reduces your RRSP room, sometimes to very little. Your notice of assessment shows what is left, and the TFSA often becomes the main personal account.
Defined contribution plans and group RRSPs
With a defined contribution plan or a group RRSP, the investment choices are yours. Leaving years of contributions in a default fund that does not fit your timeline is a quiet, expensive mistake. Take the full employer match first, because it is an immediate return.
Changing employers: commuted value or deferred pension
Leaving a defined benefit plan before retirement usually means choosing between a deferred pension and a lump sum commuted value. Only part of a large commuted value can move tax-free to a locked-in account; the excess over the Income Tax Act limit is paid in cash and taxed. Compare both before you sign the election.
Shares in an employee-owned firm
Some engineering and consulting firms are owned by their employees and offer shares to senior staff, sometimes with a loan from the firm. Those shares are illiquid and tied to the same employer as your salary and pension, so they need a place in the plan and a limit.
Should engineers incorporate?
An engineer on salary cannot move employment income into a corporation. Consulting engineers can, and in Alberta, British Columbia and Ontario the practice rules come from the provincial regulator.
APEGA permits and provincial rules
In Alberta, a corporation that practises engineering needs a permit to practice from APEGA. British Columbia requires the firm to register with Engineers and Geoscientists BC, and Ontario requires a certificate of authorization from Professional Engineers Ontario. Engineering corporations are ordinary business corporations rather than professional corporations, so share ownership is not limited the way it is for lawyers or physicians.
The personal services business trap
A one-person corporation that does the work an employee would do for a single client risks being treated as a personal services business. That income loses the small business rate, is taxed federally at 33% before provincial tax, and most deductions are denied. Several clients, your own tools and real business risk are what separate a consulting firm from a disguised employee.
Salary or dividends from your consulting corporation
Once the corporation exists, the pay mix decides your RRSP room, your CPP and how much stays invested. A salary of about $188,000 creates the full 2026 RRSP limit of $33,810 the following year; dividends leave more capital in the corporation.
Liability and insurance for consultants
Consulting engineers carry professional liability exposure that an employer used to cover. Liability coverage, disability insurance and a clear line between personal and corporate assets all belong in the plan.
Retirement planning for engineers
Engineers often retire with two or three pensions from different employers, a group RRSP and personal savings. The work is fitting them into one income.
Choosing an early retirement date
Many defined benefit plans reduce the pension for each year you retire before the plan's unreduced age. The difference between leaving at 55, 58 or 60 can be large and permanent, so price each date against what you would earn by staying.
Pension options at retirement
Single life or joint and survivor, with or without a guarantee period. Pension law generally requires a joint and survivor pension when you have a spouse, unless your spouse signs a waiver. The choice sets your spouse's income for life and cannot be changed once payments start.
Pension income splitting
Up to half of eligible pension income can be split with a spouse on your tax returns. Income from a registered pension plan qualifies at any age; RRIF income qualifies from 65. The best split often changes from year to year.
Bridging to CPP and OAS
Some pensions include a bridge benefit that stops at 65. Planning for that drop, and deciding whether to defer CPP to 70 for a payment 42% larger, keeps income level when the bridge ends. RRSP withdrawals in the bridge years can do the same job.
“Why would you wait until the government forces you to withdraw at the worst possible time when you could take control earlier and do it on your own terms?”
Kaetyn St. Hilaire, CFA, in The ONE Trick Can Save Canadian Retirees Thousands in Taxes
Questions from engineers
Straight answers to the questions people search for most.
It depends on your health, your other income, how much of the value would be paid as taxable cash and whether you want to carry the investment and longevity risk yourself. The commuted value calculator projects the lump sum so you can compare it with the pension.
Yes. A corporation that practises engineering needs an APEGA permit to practice. Incorporating only helps when you have business income rather than salary, and can leave some of it invested inside the corporation.
Your pension adjustment is reported on your T4 and reduces next year's RRSP room. Members of generous defined benefit plans can be left with very little room, which makes the TFSA more important.
You keep the benefits you have earned. You usually choose between a deferred pension and transferring the commuted value, partly to a locked-in account. Severance is taxed separately as a retiring allowance.
A group RRSP with an employer match is usually where the first dollar goes, because the match is an immediate return. Beyond the match, a personal RRSP often offers wider investment choices.
Yes. We work with clients in Calgary and across Canada, in person in Calgary and by video meeting everywhere else.
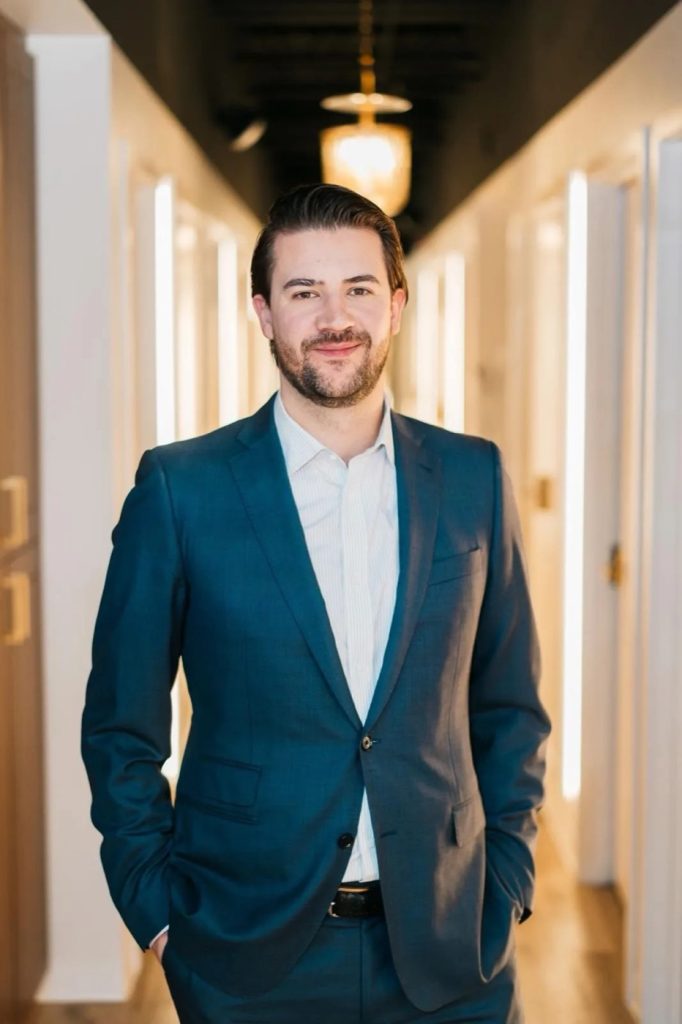
Kaetyn St. Hilaire, CFA
Kaetyn is a Calgary-based financial advisor who works with high earners and medical professionals, particularly physicians and dentists navigating the financial complexities that come with high-income careers. He focuses on actionable strategies: the salary-dividend mix inside a professional corporation, RRSP and TFSA contributions, and a long-term investment plan.
Designations
CFA, CIM, CIWM, FCSI, CEA
Book a free wealth review
A complimentary, no-obligation conversation about your pension, your career and your goals, and a clear explanation of how we can help.