Estate planning in Alberta
Insurance and estate planning in Alberta for physicians, business owners and high earners. Protection strategies that safeguard your family and preserve your legacy: the right coverage, the right beneficiary designations, and an estate plan built for Alberta's rules, coordinated with your lawyer and accountant.
What insurance and estate planning covers
Estate planning is where tax planning, insurance and investment strategy meet. It is not just about having a will.
Life and disability insurance
Life and disability insurance analysis, with coverage tailored to your income and obligations.
Critical illness coverage
Critical illness coverage, reviewed alongside your life and disability insurance.
Estate planning and wealth transfer
Planning for the tax at death, the spousal rollover and how wealth passes to the next generation.
Insurance within corporate structures
Corporate-owned life insurance and the capital dividend account, for business owners and incorporated professionals.
Beneficiary and succession planning
Beneficiary designations on RRSPs, RRIFs, TFSAs and insurance policies, and succession for a business or practice.
What is different in Alberta
The tax consequences at death are federal and the same in Calgary or Toronto. The rules on wills, powers of attorney, dependant claims and probate are provincial, and Alberta's are distinct.
Alberta charges a flat fee for a grant of probate, to a maximum of $525 regardless of estate size, so avoiding probate is rarely a main goal here. Probate is still a public process, so privacy can be a reason to hold some assets outside the will.
Alberta's 2012 Wills and Succession Act lets a court validate a will that does not meet the formal requirements if it is satisfied the document reflects the deceased's intentions. In some circumstances it also revokes gifts to a former spouse or adult interdependent partner when the relationship ends, unless the will says otherwise. If you are separating, review your will right away.
Alberta uses a personal directive for health care and personal decisions and an enduring power of attorney for financial matters. Documents drafted under another province's law may need legal work before Alberta institutions accept them, so if you have moved here, have them reviewed under Alberta law.
Two people who have lived together in a relationship of interdependence for three or more years, who live together with some permanence and have a child together, or who have signed an adult interdependent partner agreement have rights similar to spouses in many areas, including claims against an estate. In blended families, life insurance, trusts and careful beneficiary designations balance those obligations.
Spouses, adult interdependent partners, minor children and in some cases adult children can ask the court for support from an estate if the will does not adequately provide for them. The will, insurance, beneficiary designations and any trusts need to work as one plan.
Your lawyer drafts the documents. We work alongside your lawyer and accountant so the insurance, the beneficiary designations and the investments fit the plan they put in place.
Taxes at death in Canada
Canada has no estate or inheritance tax in the traditional sense. The tax comes through your final return, and the earlier you plan, the more tools you have.
The CRA treats you as having sold everything at fair market value immediately before death. Capital gains on a non-registered portfolio, rental property, vacation home or private company shares are taxed on your final return.
The full value of an RRSP or RRIF is income on the final return, not just the growth. Left to a spouse or common-law partner, it can roll over tax-deferred. Left to independent adult children, there is no rollover, and the estate pays the tax.
Assets left to a surviving spouse roll over at their cost, which defers the tax to the second death. That is why the drawdown strategy and the estate plan are the same conversation.
Name your spouse or common-law partner as successor holder, not beneficiary. As successor holder, the account stays a TFSA, keeps growing tax-free and does not use any of the survivor's own contribution room.
Permanent life insurance pays a tax-free death benefit that can cover the tax at death without forcing assets to be sold. When a corporation owns the policy, the death benefit can generally be paid out to shareholders tax-free through the capital dividend account.
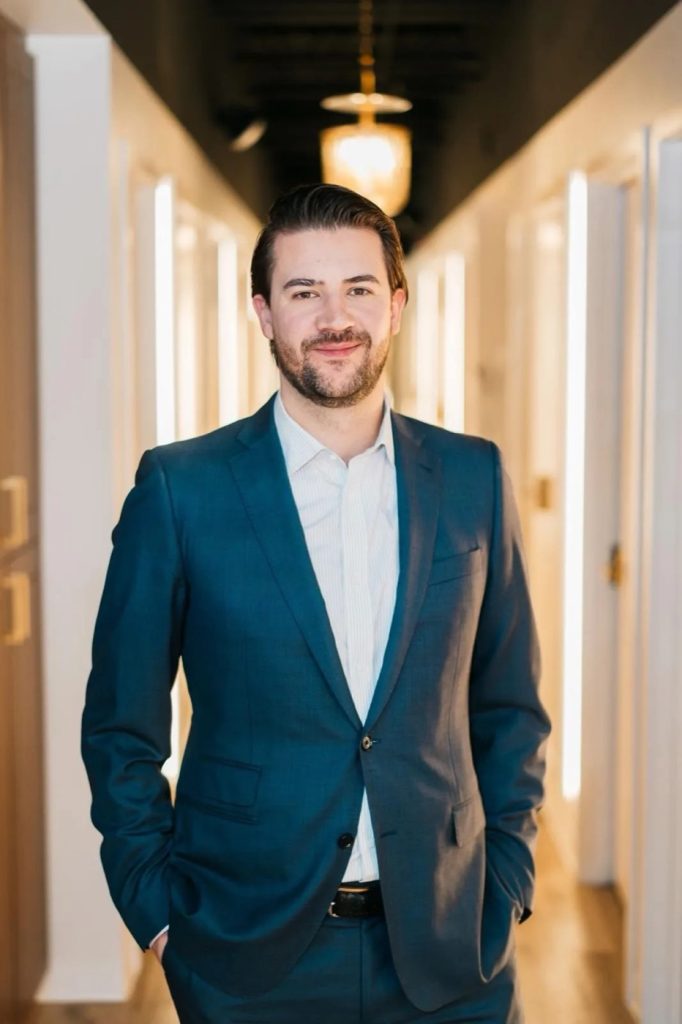
Kaetyn St. Hilaire, CFA
Kaetyn is a Calgary-based financial advisor who works with high earners and medical professionals. He is a Certified Executor Advisor (CEA), a designation focused on estate settlement and executor responsibilities, so wealth transfer and estate administration go smoothly.
Designations
CFA, CIM, CIWM, FCSI, CEA
Estate planning questions
Honest answers to the questions we hear most often.
Not in the traditional sense. Instead, you are deemed to have sold your assets at fair market value immediately before death. The capital gains, and the full value of RRSPs and RRIFs, are taxed on your final return unless they roll over to a spouse or common-law partner.
Alberta's fee for a grant of probate is a flat amount capped at $525, whatever the size of the estate. In Ontario, by comparison, the Estate Administration Tax is 1.5% of the estate's value above $50,000.
Yes. Designations on RRSPs, RRIFs, TFSAs and insurance policies pass those assets directly to the person named, outside the will and outside probate. Review them every year. An outdated designation, an ex-spouse for example, can take years to untangle.
Alberta's term for a partner who is not a married spouse: someone you have lived with in a relationship of interdependence for three or more years, or with some permanence if you have a child together, or with whom you have signed an adult interdependent partner agreement. They can claim against your estate whatever your will says.
Your estate lawyer. Wills, personal directives and enduring powers of attorney must comply with Alberta law. We work alongside your lawyer and accountant so the tax-efficient structure and the legally sound structure are the same structure.
Now. It doesn't need to be perfect on day one, but it does need to start. Insurance costs least when you are young and healthy; every year of delay raises premiums and the risk of a health condition that makes you uninsurable.
Book a free wealth review
A complimentary, no-obligation review of your insurance, beneficiary designations and estate plan, and a clear explanation of what to fix first.