Financial advisor for business owners
Financial planning for owners of incorporated businesses. Kaetyn St. Hilaire, CFA, connects the business to your personal plan: how you pay yourself, retained earnings, an individual pension plan and the sale that funds your retirement, for owners in Calgary and across Canada. For the structure itself, see corporate planning.
Salary vs dividends for business owners
How you pay yourself decides what the business builds for you outside it: RRSP room, CPP, an IPP or retained capital.
What salary builds
Salary is deductible to the corporation and creates RRSP room at 18% of earned income. A salary of about $188,000 creates the full 2026 limit of $33,810 the following year. It also brings CPP contributions on both the employer and employee side.
What dividends build
Dividends are paid from after-tax corporate income and are not deductible. They create no RRSP room and no CPP, but they leave more capital inside the corporation and let you choose the year you take income.
The passive income grind
Once the corporation's adjusted aggregate investment income passes $50,000 in a year, its $500,000 small business limit shrinks by $5 for every $1 over, and is gone at $150,000. How retained earnings are invested matters as much as how much is retained.
Family members and TOSI
Dividends to a spouse or adult children who are not actively engaged in the business are generally taxed at the top rate under the tax on split income rules. The exceptions, for actively engaged family, excluded shares in non-service businesses and a spouse once the owner is 65, need to be documented.
Individual pension plans for business owners
An IPP is a defined benefit pension registered for the owner of a corporation. It turns salary into a larger, deductible retirement contribution.
When an IPP makes sense
For owners in their late forties and beyond who pay themselves a T4 salary, an IPP typically allows substantially larger deductible contributions than an RRSP. The corporation funds it, deducts it and may be able to fund past years of service.
The trade-offs
An IPP needs actuarial valuations, annual filings and ongoing contributions, and its assets are locked in. It also moves capital out of the passive income calculation, which can protect the small business rate.
IPP or RRSP
An IPP takes the place of the RRSP for the years it covers, and the pension adjustment it creates leaves little RRSP room. The comparison turns on your age, your salary history and how long you will keep drawing a salary.
Corporate-owned life insurance
For owners with retained earnings, properly structured permanent life insurance owned by the corporation can grow on a tax-deferred basis outside the passive income rules. On death, much of the benefit can be paid out tax-free through the capital dividend account.
Selling your business and retirement planning for business owners
For most owners the business is the largest asset in the retirement plan. How and when it is sold can be the largest tax decision of a career.
Share sale or asset sale
Buyers often prefer assets; sellers usually prefer shares, because a share sale can use the lifetime capital gains exemption. The difference in after-tax proceeds can run to hundreds of thousands of dollars.
Qualifying for the lifetime capital gains exemption
The exemption, $1.25 million since June 2024, applies to shares of a qualified small business corporation: at least 90% of assets used in an active business at the sale, more than 50% throughout the 24 months before it, and shares held for 24 months. Surplus investments may need to move to a holding company first.
Starting two to three years before the sale
Purifying the balance sheet, reviewing who owns shares and planning where the proceeds will be invested all take time. Problems fixed early are cheap; on short notice some cannot be fixed at all.
Retirement income after the sale
Sale proceeds, a holding company, RRSPs, an IPP, CPP and OAS each have their own tax treatment. Drawing them in the right order, rather than spending the sale cash first, can keep you in lower brackets for longer.
“The best time to plan for capital gains tax is years before you actually need to trigger the gain. Not after. Not when you need the money.”
Kaetyn St. Hilaire, CFA, in Canada's Capital Gains Tax: The Silent Killer of Your Wealth?
Questions from business owners
Straight answers to the questions people search for most.
Usually some of each. Salary builds RRSP room, CPP and IPP capacity; dividends keep capital in the corporation and add flexibility. In Alberta the total tax on either route is close, so the choice comes down to what you want each one to build.
A defined benefit pension for the owner of a corporation who draws a salary. It generally suits owners in their late forties and older with steady income and a long horizon.
When the corporation's adjusted aggregate investment income passes $50,000 in a year. It depends on the income the investments produce, not the size of the account.
A share sale produces a capital gain, half of which is taxable, and the lifetime capital gains exemption ($1.25 million since June 2024) can shelter it if the shares qualify. An asset sale is taxed in the corporation and again when the proceeds are paid out.
Corporate planning is the structure: holding companies, corporate investments, insurance and extraction. This page is about you as the owner: pay, pension, sale and retirement. Most owners need both, planned together.
We generally work with clients who have $500,000+ in investable assets or a household income of $200,000+. That said, we're happy to have an introductory conversation regardless. Sometimes the right time to start planning is before you've accumulated significant wealth.
Kaetyn St. Hilaire, CFA
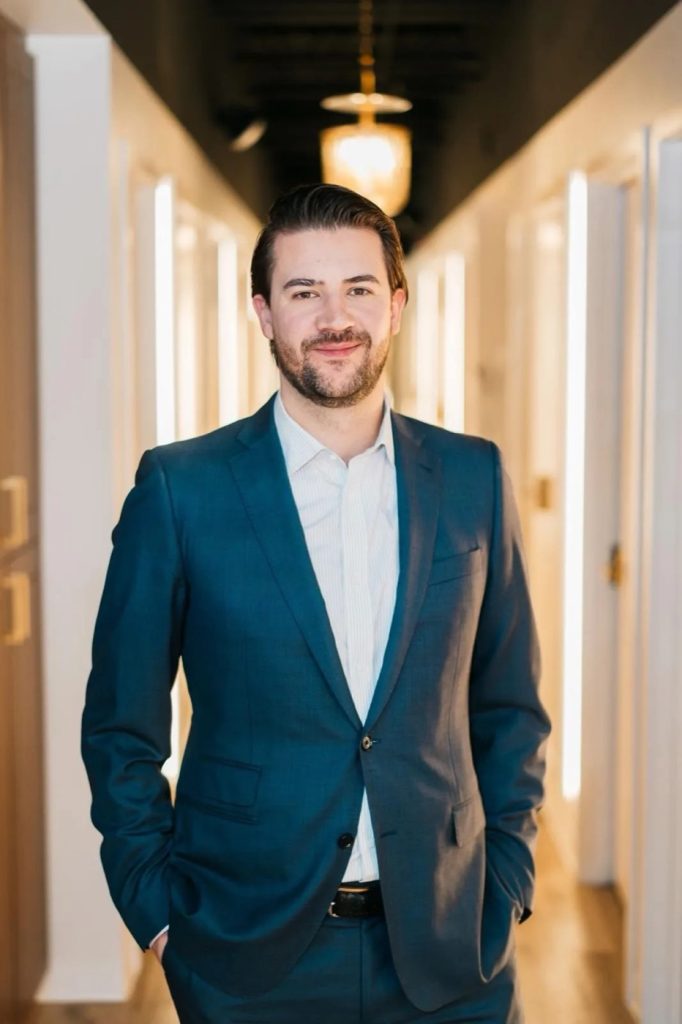
Kaetyn is a Calgary-based financial advisor who works with high earners and medical professionals, particularly physicians and dentists navigating the financial complexities that come with high-income careers. He focuses on actionable strategies: the salary-dividend mix inside a professional corporation, RRSP and TFSA contributions, and a long-term investment plan.
Designations
CFA, CIM, CIWM, FCSI, CEA
Book a free wealth review
A complimentary, no-obligation conversation about your business, your corporation and your goals, and a clear explanation of how we can help.