Financial advisor for tech professionals
Financial planning for software engineers, product leaders and founders paid in salary, RSUs, ESPP shares and stock options, often from a US employer. Kaetyn St. Hilaire, CFA, turns that pay into a tax-aware plan, for tech professionals in Calgary and across Canada.
RSUs, ESPPs and stock options in Canada
Tech pay often arrives in three or four forms, each taxed differently in Canada and reported by a US brokerage that does not know Canadian rules.
How RSUs are taxed in Canada
Restricted stock units are employment income on their full value when they vest, converted to Canadian dollars at that day's exchange rate. That value becomes your cost base, so only later growth is a capital gain. Brokerage statements show US dollar cost; your Canadian cost base has to be tracked in Canadian dollars.
Employee stock purchase plans
In an ESPP, any discount and any employer contribution is a taxable benefit, generally when the shares are bought. US plans built for American tax rules, such as section 423 plans, do not get the same treatment in Canada.
Startup stock options
Options from a Canadian-controlled private corporation are not taxed when you exercise. Tax is deferred until you sell the shares, and if you hold them for at least two years after exercise, half the benefit can be deducted. Public company options are taxed at exercise.
Withholding that falls short
Shares sold to cover tax at vesting often do not cover the tax owing at your actual marginal rate. Large vests can leave a balance owing in April and, if it repeats, CRA instalment reminders.
“Pull a report showing the adjusted cost base of every investment you own outside of registered accounts. You cannot plan around gains you haven't measured.”
Kaetyn St. Hilaire, CFA, in Canada's Capital Gains Tax: The Silent Killer of Your Wealth?
US stock, withholding tax and foreign reporting
Most tech equity is US listed and held at a US brokerage. That brings reporting and tax rules that are easy to miss.
Foreign property reporting (T1135)
If the total cost of your specified foreign property, including US employer shares held at a US brokerage, is more than $100,000 at any time in the year, you file form T1135 with your return. Penalties for late filing apply even when no tax is owing. Property in an RRSP or TFSA is excluded.
US dividends and US estate tax
US dividends paid to a Canadian generally lose 15% to US withholding under the tax treaty. It can be claimed as a foreign tax credit in a taxable account, not in a TFSA, and does not apply in an RRSP. Large holdings of US shares can also expose your estate to US estate tax, depending on the size of your worldwide estate.
Currency and your cost base
Each vest, purchase and sale is converted to Canadian dollars at the exchange rate for that day. A weaker Canadian dollar can create a taxable gain in Canadian dollars even when the share price has not moved.
Selling at a loss between vests
Selling employer shares at a loss and receiving identical shares within 30 days, before or after the sale, can make the loss superficial: it is denied and added to the cost of the new shares. Regular vests make this easy to trigger by accident.
Building wealth beyond your employer's stock
The goal is to turn equity into a diversified plan without paying more tax than you need to.
A selling plan for vested shares
Holding vested RSUs is the same as buying your employer's stock with your bonus. Deciding in advance how much of each vest to keep, and selling the rest at vest when the gain is smallest, limits both the risk and the tax.
RRSP vs TFSA in a big vest year
A large vest pushes income into a top bracket, which makes an RRSP contribution worth more that year. The RRSP limit for 2026 is $33,810, and unused room carries forward.
Should tech contractors incorporate?
Contractors with several clients can benefit from a corporation and Alberta's 11% small business rate. A contractor with one client, working like an employee, risks the personal services business rules: income taxed federally at 33% before provincial tax, with most deductions denied.
Retirement planning for tech professionals
Tech careers can build capital early and then change quickly. A plan with a target for financial independence, rather than a fixed retirement age, lets you take a sabbatical, a startup role or an early exit on your own terms.
Questions from tech professionals
Straight answers to the questions people search for most.
As employment income at vesting, on the full market value converted to Canadian dollars. Growth or loss after that is a capital gain or loss when you sell.
Yes, if the cost of all your specified foreign property is more than $100,000 at any time in the year. Shares held in an RRSP or TFSA are excluded.
Selling at vest locks in a cost base close to the sale price, so there is little extra tax, and it removes concentration risk. Keeping the shares is a separate investment decision.
Yes. The discount is a taxable employment benefit, generally when you buy the shares, even if the plan qualifies for special treatment under US rules.
US dividends in a TFSA lose 15% to US withholding tax that cannot be recovered. An RRSP is generally exempt. See the hidden cost of US investments in a TFSA.
Yes. We work with clients in Calgary and across Canada, in person in Calgary and by video meeting everywhere else.
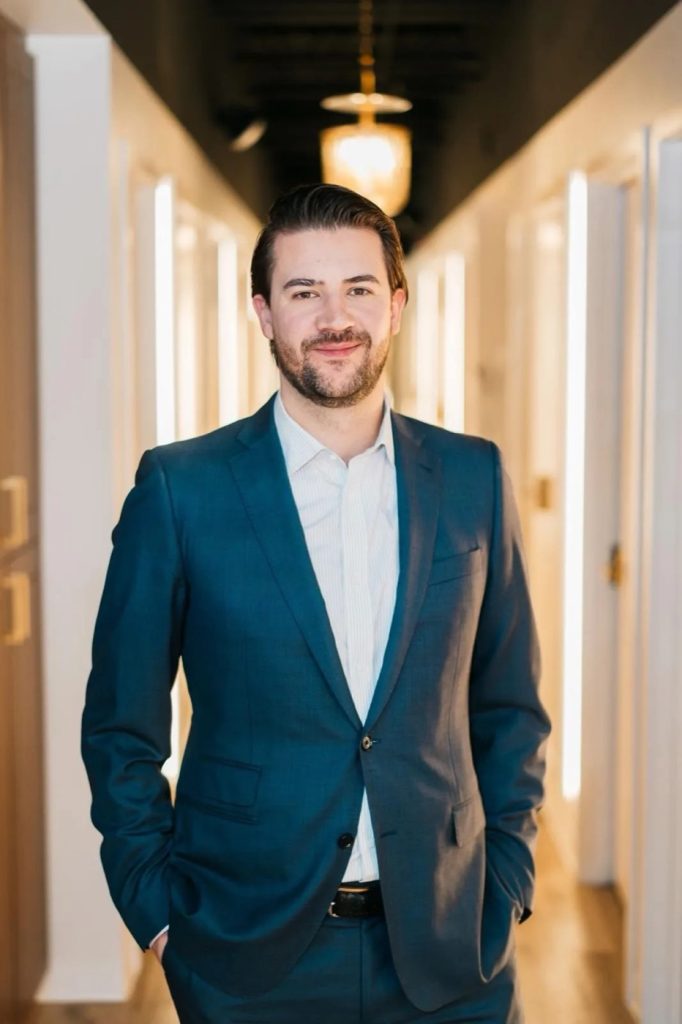
Kaetyn St. Hilaire, CFA
Kaetyn is a Calgary-based financial advisor who works with high earners and medical professionals, particularly physicians and dentists navigating the financial complexities that come with high-income careers. He focuses on actionable strategies: the salary-dividend mix inside a professional corporation, RRSP and TFSA contributions, and a long-term investment plan.
Designations
CFA, CIM, CIWM, FCSI, CEA
Book a free wealth review
A complimentary, no-obligation conversation about your equity, your taxes and your goals, and a clear explanation of how we can help.