Financial advisor for executives
Financial planning for executives whose pay arrives in more forms than salary. Kaetyn St. Hilaire, CFA, plans around stock options, RSUs, PSUs, DSUs and deferred compensation so that each vest, exercise and payout lands in the right tax year, for executives in Calgary and across Canada.
Stock options, RSUs and PSUs for executives
Equity compensation is taxed as employment income first and investment income second. The order, the timing and the concentration risk all need a plan.
Employee stock options
For a public company, the benefit is taxed as employment income when you exercise: the share value less the exercise price. If the option meets the conditions, half of that benefit is deducted, so it is taxed like a capital gain. At large employers, options vesting over $200,000 a year, measured at grant, may not qualify for the deduction.
Restricted and performance share units
RSUs and PSUs are taxed as employment income on their full value when they vest and pay out. Most plans settle within three years to stay outside the salary deferral rules. Any shares you keep start a new cost base, and later growth is a capital gain.
Deferred share units
DSUs, common for directors and senior executives of public companies, are paid only after you leave and must be settled by the end of the year after the year you leave. Choosing the payout year can move a large amount of income into a year with less of it.
Concentration risk
Salary, bonus, unvested awards and often a pension all depend on one company. Holding more of the same stock personally compounds the risk. A selling schedule set in advance, inside your company's trading windows, keeps decisions away from the headlines.
“Deferral feels like winning, but deferral is not the same as avoidance.”
Kaetyn St. Hilaire, CFA, in Paying Too Much in Taxes? Here's How Wealthy Canadians Legally Pay Less
Deferred compensation and executive pensions
Above the registered limits, executive pay often moves into arrangements that pay later. Each one has its own tax timing and its own credit risk.
Supplementary pensions
Registered pensions are capped by the Income Tax Act, so many employers promise a top-up through a supplementary executive retirement plan. It is often unfunded, or secured through a retirement compensation arrangement where half of each contribution is held as a refundable tax. An unfunded promise depends on your employer's health, so know which kind yours is.
Bonus deferral and the three year rule
A bonus can usually be deferred if it is paid within three years after the end of the year it was earned. Moving a bonus into a year of lower income, such as the year after you retire, can lower the rate it is taxed at.
Change of control terms
Many executive agreements accelerate vesting or pay severance when the company is sold and your role changes. Knowing the terms in advance lets you plan for a large, sudden payout rather than react to one.
Giving appreciated shares to charity
Donating publicly listed shares directly to a registered charity removes the capital gain on them and still produces a receipt for their full value. For executives holding low-cost shares, it is often the most tax-efficient way to give.
Retirement planning for executives
An executive's retirement is rarely one date. Vesting schedules, change of control terms and non-compete periods shape when you can leave and what you leave with.
Leaving with unvested awards
Retirement, resignation and termination are often treated differently in award agreements. Some plans keep vesting for retirees who meet an age and service test; others forfeit everything unvested. Read the definitions before you set a date.
Severance and retiring allowances
Severance is taxed as a retiring allowance. Only service before 1996 allows a tax-free transfer to an RRSP, so most of a modern package is taxed in the year it is paid unless it can be spread over two tax years.
Should executives incorporate?
Not for salary. Employment income cannot be earned through a corporation, and routing it through one invites the personal services business rules. A corporation becomes relevant later, for consulting after you leave, when there is genuine business income from more than one client.
Protecting OAS in retirement
Pensions, deferred payouts and RRIF withdrawals can push retirement income past the OAS recovery threshold, where OAS is clawed back at 15 cents for each dollar above it. Timing deferred compensation and RRSP withdrawals before OAS starts can protect it.
Questions from executives
Straight answers to the questions people search for most.
There is no single rule. The decision weighs the time left to expiry, your view of the company, how much of your wealth is already in its shares and your tax bracket this year and next. Exercising across several years can keep more of the benefit out of the top bracket.
No. The value at vesting is employment income and becomes the cost base of the shares. Only growth after that date is a capital gain when you sell. The trap is assuming the shares withheld at vesting covered all of the tax.
As employment income when they are paid out, which happens only after you leave the company and by the end of the following calendar year. The payout year is the main planning lever.
Yes. The proposed increase to the capital gains inclusion rate was cancelled in 2025, and the stock option deduction remains one half of the benefit for options that qualify.
Holding vested shares is the same as buying them with cash on the vest date. If you would not buy that amount of your employer's stock today, a selling plan is worth considering.
We generally work with clients who have $500,000+ in investable assets or a household income of $200,000+. That said, we're happy to have an introductory conversation regardless. Sometimes the right time to start planning is before you've accumulated significant wealth.
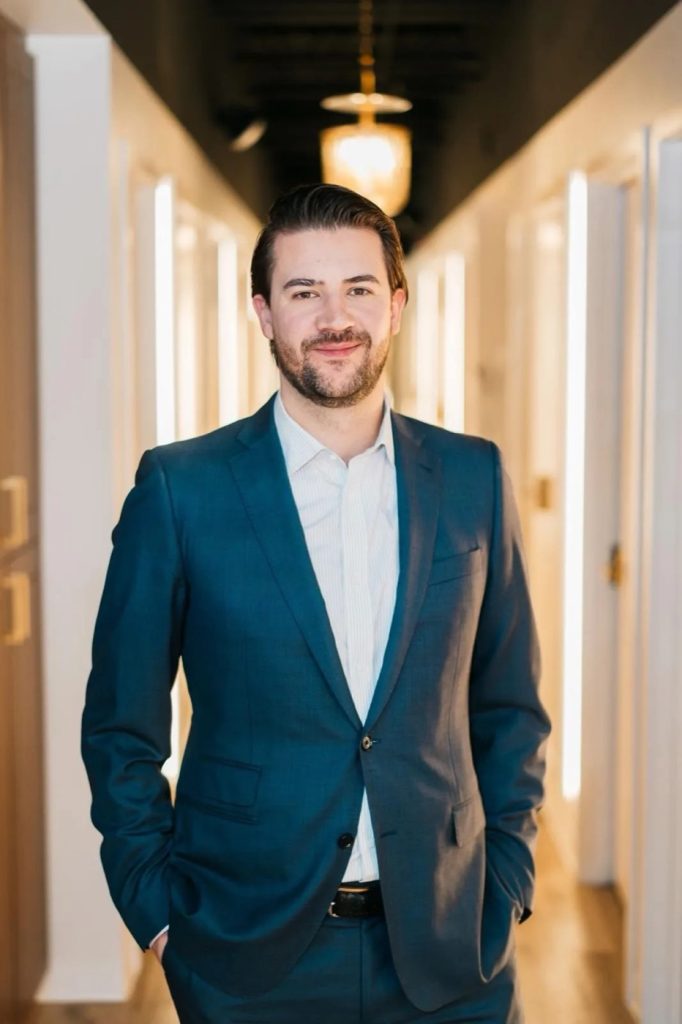
Kaetyn St. Hilaire, CFA
Kaetyn is a Calgary-based financial advisor who works with high earners and medical professionals, particularly physicians and dentists navigating the financial complexities that come with high-income careers. He focuses on actionable strategies: the salary-dividend mix inside a professional corporation, RRSP and TFSA contributions, and a long-term investment plan.
Designations
CFA, CIM, CIWM, FCSI, CEA
Book a free wealth review
A complimentary, no-obligation conversation about your compensation, your equity and your goals, and a clear explanation of how we can help.