Financial advisor for high income earners
Financial planning for high income earners and HENRYs: high earners, not rich yet. Kaetyn St. Hilaire, CFA, turns a large income into lasting wealth with a plan for tax, savings, the RRSP and TFSA decision and the OAS clawback years ahead, for clients in Calgary and across Canada.
Financial planning for HENRYs
HENRYs are professionals earning $150K to $500K+ who are building wealth rapidly but need a structured plan to maximize every dollar. A high income is not the same as a high net worth, and the gap closes only with a plan.
Why high earners feel behind
Top marginal rates, a late start after years of education, housing costs and spending that rises with income can leave a high-earning household saving less than it expects. The fix starts with a real savings rate, measured every year.
The marginal rate that matters
In 2026 the top combined rate is 48% in Alberta, 53.5% in British Columbia and 53.53% in Ontario. Every deduction, and every dollar of income moved to a lower bracket or a later year, is worth that rate.
Lifestyle creep
Fixing savings as a share of each raise, before it reaches your chequing account, lets you enjoy a higher income without spending all of it. Automatic RRSP, TFSA and RESP contributions on payday do the work that willpower does not.
Income splitting with a spouse
Spousal RRSPs, a prescribed rate loan to a lower-income spouse and, later, pension income splitting all move income to the lower bracket. Each comes with attribution rules that have to be followed exactly.
RRSP vs TFSA for high income earners
For most high earners the answer is both, in the right order, with the taxable account planned too.
When the RRSP wins
An RRSP deduction is worth your marginal rate today, and withdrawals are taxed at your rate in retirement. Contribute at 48% and withdraw at 30%, and the difference is a real gain. The 2026 limit is $33,810, or 18% of last year's earned income if less.
Why the TFSA still matters
TFSA withdrawals are tax-free and do not count as income for the OAS clawback. For a high earner headed for a large retirement income, the TFSA is often the account that protects OAS and keeps flexibility. The 2026 TFSA limit is $7,000.
The taxable account
Once registered room is full, the taxable account carries the rest. Only half of a capital gain is taxed and eligible Canadian dividends receive the dividend tax credit, while interest is fully taxable, so what you hold there matters.
RESPs for children
The Canada Education Savings Grant adds 20% on the first $2,500 contributed each year per child, up to $500 a year and $7,200 per child over their lifetime. It is one of the few guaranteed returns available.
“Wealthy Canadians do not treat the TFSA as an emergency fund. They treat it as a precision tool to control exactly how much taxable income they report each year.”
Kaetyn St. Hilaire, CFA, in Paying Too Much in Taxes? Here's How Wealthy Canadians Legally Pay Less
The OAS clawback and retirement planning for high income earners
High earners often build retirement incomes large enough to lose some or all of their Old Age Security. Planning for it early changes the outcome.
How the OAS clawback works
Once net income passes the OAS recovery threshold, about $95,323 for 2026, OAS is reduced by 15 cents for each dollar above it until it is gone. RRIF withdrawals, pensions, grossed-up dividends and the taxable half of capital gains all count.
Drawing down RRSPs before OAS
RRSP withdrawals in lower-income years before 71, moved to a TFSA where room allows, shrink the RRIF that would later trigger the clawback. Deferring OAS to 70 also raises it by 36%.
Should high income earners incorporate?
Only business or professional income can be earned through a corporation; employees cannot incorporate their salary. For self-employed professionals and owners who leave money invested, Alberta's 11% small business rate is a powerful deferral.
Retirement planning for high income earners
The question is not only how much, but how the money will come out: which accounts, in which order and at what tax rate, with CPP and OAS timed around the rest.
“The question is never whether you'll pay tax on your registered accounts. The question is what rate you'll pay and whether that decision is yours or the government's.”
Kaetyn St. Hilaire, CFA, in Paying Too Much in Taxes? Here's How Wealthy Canadians Legally Pay Less
Questions from high income earners
Straight answers to the questions people search for most.
High Earner, Not Rich Yet: a professional with a high income who has not yet built a matching net worth, typically earning $150K to $500K+.
Usually the RRSP first when your marginal rate today is well above your expected rate in retirement, then the TFSA. The RRSP vs TFSA calculator compares the two at your rates.
At the OAS recovery threshold, about $95,323 of net income for 2026, indexed each year. Above it, 15% of the excess is repaid until the full OAS is gone.
Use RRSP room fully, split income with a spouse where the rules allow, hold each investment in the right account and time income into lower-rate years. For business owners, a corporation adds deferral.
Not by rule, but at that income each decision is worth more: a misplaced contribution, an unplanned bonus or an OAS clawback later. We generally work with clients who have $500,000+ in investable assets or a household income of $200,000+.
Compare the after-tax return you would need with your mortgage rate. The pay off mortgage or invest calculator runs the comparison with your figures.
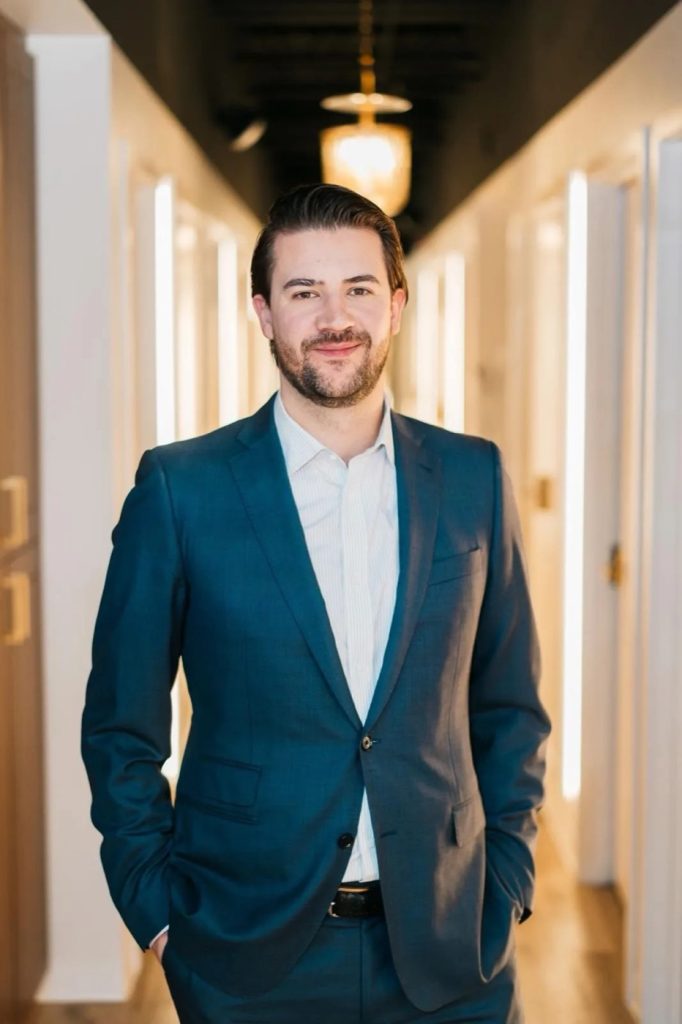
Kaetyn St. Hilaire, CFA
Kaetyn is a Calgary-based financial advisor who works with high earners and medical professionals, particularly physicians and dentists navigating the financial complexities that come with high-income careers. He focuses on actionable strategies: the salary-dividend mix inside a professional corporation, RRSP and TFSA contributions, and a long-term investment plan.
Designations
CFA, CIM, CIWM, FCSI, CEA
Book a free wealth review
A complimentary, no-obligation conversation about your income, your savings and your goals, and a clear explanation of how we can help.